
European industrial companies are looking for additional manufacturing locations as they respond to rising costs, supply-chain disruption and excessive dependence on a limited number of suppliers.
Vietnam is increasingly included in this search. The country is already an established manufacturing centre for electronics, textiles and consumer goods, while its mechanical engineering base has also expanded into industrial frames, welded assemblies, equipment supports and fabricated components.
Interest in Vietnam steel fabrication, however, does not mean that the country is suitable for every project. Its competitiveness depends on the product, technical requirements, available materials and the type of manufacturer involved.
European Companies Are Diversifying Their Supply Chains
For many European manufacturers, diversification does not involve moving an entire product line away from an existing supplier.
A machinery company may retain engineering and final assembly in Europe while outsourcing machine frames or access platforms. An equipment producer may qualify a Vietnamese manufacturer as a second source for selected modules. Other companies may begin with prototypes or limited production before transferring larger volumes.
This gradual approach makes Vietnam a practical option. European companies can test local capabilities without immediately restructuring their whole supply chain.
The strongest demand generally comes from businesses with established drawings and repeatable technical requirements. Vietnam is less suited to projects where the manufacturer is expected to develop an incomplete product concept independently.
This video explains some of the key steps involved in assessing a factory’s capabilities and conducting an audit before moving into production:
A Broad but Fragmented Supplier Market
Vietnam has a large mechanical and metalworking sector, but the market is not uniform.
One group consists of construction-oriented companies producing beams, columns, roofing systems and pre-engineered buildings. These suppliers may have considerable capacity, although their processes are usually designed around construction projects rather than customised industrial equipment.
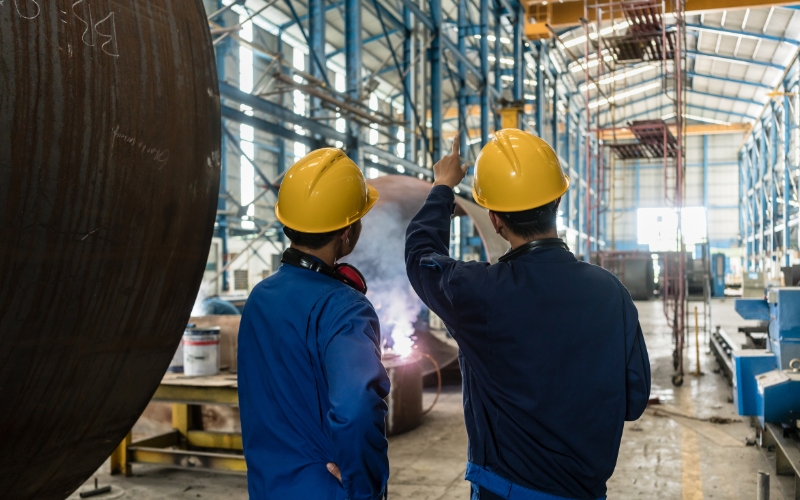
A second group focuses on industrial fabrication. Typical products include platforms, stairways, skids, machine frames, tanks, conveyors and equipment supports. These manufacturers are often better aligned with European outsourcing projects because they already work from customer drawings.
The market also includes mechanical engineering companies that combine fabrication with machining, assembly, hydraulics or electrical integration. They may be suitable for complete equipment modules but have less capacity for very large structural packages.
Smaller specialists provide cutting, bending, coating, galvanising and non-destructive testing. Many manufacturers use this subcontracting network instead of performing every process internally.
This creates flexibility but also reduces visibility. A company may present itself as a complete manufacturer while relying heavily on external processors. The quality of the final product therefore depends on both the main supplier and its supporting network.
Manufacturing Capabilities Vary by Region

Steel Fabrication Regions in Vietnam
Vietnam’s industrial activity is concentrated around several manufacturing clusters.
Northern Vietnam benefits from proximity to China, established industrial supply chains and access to ports around Hai Phong. The region can be suitable for projects that require imported components or coordination with other Asian suppliers.
Southern Vietnam has a diverse network of mechanical engineering companies, metal processors, surface-treatment providers and logistics services. Ho Chi Minh City and neighbouring industrial provinces offer a broad supplier base for projects involving several manufacturing stages.
Central Vietnam has a smaller industrial network but can provide alternatives for selected projects. Costs may be competitive, although access to specialised suppliers and supporting services is less extensive.
Location therefore affects more than freight. It influences access to materials, machining capacity, skilled labour, inspection services and export infrastructure.
A supplier located within a strong industrial cluster may manage a complex project better than a larger but isolated plant.
Where Vietnam Is Most Competitive
Vietnam’s advantage is strongest when labour and fabrication work represent a significant share of the final product’s value.
Suitable products may include:
- Machine frames and equipment bases.
- Industrial platforms and access systems.
- Welded modules and support assemblies.
- Skids, conveyors and material-handling components.
- Customised parts manufactured from client drawings.
These products usually require several stages, such as cutting, forming, fitting, welding, grinding, inspection and surface treatment. Lower operating costs can create a meaningful advantage when these processes require substantial skilled labour.
Medium-volume and customised projects may be particularly suitable. Some Vietnamese manufacturers are willing to handle orders that are too specialised for high-volume Asian plants but too labour-intensive to produce competitively in Europe.
Logistics remain an important consideration. Products that can be divided into modules or shipped in containers are generally easier to outsource than very large finished structures.
By contrast, technically simple but extremely heavy products may offer limited savings because raw materials and freight account for most of the delivered cost.
Projects requiring uncommon grades can also face longer lead times. Vietnam has strong availability in common construction products, but certain specialised inputs may need to be imported.
Important Gaps Remain
Vietnam’s core strength lies in manufacturing execution. Common limitations appear in engineering support, documentation and complete project management.
Some suppliers can produce accurately from detailed drawings but are less capable of developing incomplete designs or resolving complex technical questions.
Documentation quality also varies. European clients may require material certificates, inspection plans, drawing revision records, non-conformity reports and full traceability. A company may have good workshop skills but limited systems for managing these records.
Standards are another dividing line. Experience with ordinary construction work does not automatically demonstrate readiness for safety-critical or regulated industrial applications.
Projects involving load-bearing components or strict welding requirements may require qualified procedures, certified personnel and documented non-destructive testing. The number of suppliers able to combine these controls with competitive pricing is smaller than the overall market suggests.
Trade and environmental requirements are also becoming increasingly relevant. European importers may need clearer information about product origin, material sources and emissions. Vietnamese suppliers that cannot provide reliable data may find it harder to serve regulated markets, even when their physical manufacturing capability is acceptable.
What European Companies Are Actually Sourcing
European interest is generally focused on selected parts of the manufacturing process rather than full relocation.
Common approaches include outsourcing:
- Labour-intensive welded assemblies.
- Frames and supporting structures.
- Platforms, stairways and access systems.
- Equipment modules manufactured from complete drawings.
- Secondary components that can be qualified before larger packages.
Many companies begin with a prototype, one product family or a second-source programme. This allows them to assess quality, communication and delivery performance before increasing the scope.
The most suitable supplier also depends on the product category. Construction-oriented companies may be appropriate for standard structural packages, while machinery projects require manufacturers with stronger machining, assembly and technical coordination.
Market research must therefore identify the correct supplier segment before individual companies are compared.
Conclusion
Vietnam is attracting greater European attention because it combines a growing industrial base with flexible manufacturing capacity and competitive operating costs.
Its opportunity is real but selective. The country is strongest in customised and labour-intensive products that can be manufactured from clear technical documentation and shipped efficiently.
The market still faces gaps in advanced engineering, specialised materials, documentation and compliance. These limitations do not prevent Vietnam from becoming a valuable manufacturing location, but they narrow the pool of suitable suppliers.
European companies are therefore unlikely to treat Vietnam as a universal replacement for existing supply markets. A more practical role is emerging: Vietnam as an additional source for selected industrial components, welded assemblies and project-based manufacturing.
Its ability to capture further demand will depend on whether local suppliers can combine workshop capability with stronger engineering support, traceability and project control.
Discover more from Vietnam Insider
Subscribe to get the latest posts sent to your email.